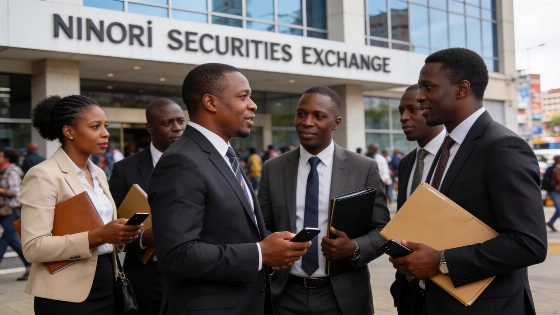
Traders in Nairobi have watched the city’s financial pulse quicken as billion-shilling deals hit the tape. In half a year, the Kenyan capital has pulled in headline IPOs and heavyweight acquisitions, shifting the region’s financial gravity.
Quickmart's IPO, approved by the Capital Markets Authority and the Nairobi Securities Exchange, opened on October 5, 2026, with trading expected to begin on November 12.
Each transaction brings its own test for the market. Quickmart’s IPO puts local investor appetite under the microscope. Private equity backers are using the listing as an exit, while the market gauges whether domestic savings can soak up a large equity float after a long drought. The offer: 2 billion existing shares, half the company, at KSh7.50 each. All proceeds go to Sokoni Retail Kenya Limited, not Quickmart. If buyers take up at least 1.5 billion shares, the IPO clears the bar. That would hand Sokoni KSh15 billion and value Quickmart at KSh30 billion, according to a Nation Africa market report. Minimum buy-in is 500 shares, or KSh3,750.
Asahi’s EABL deal shows global players still see value in East African consumer brands, even with currency swings and inflation risk. Access Bank’s move on National Bank of Kenya fits a wider pattern: pan-African banks are scaling up through M&A to build resilience. Safaricom’s shift to debt instruments and commercial paper is deepening the corporate bond market and setting new benchmarks for cost and transparency.
International institutional investors have shown interest in Quickmart's IPO, with the International Finance Corporation (IFC) conditionally committing up to US$15 million (about KSh1.94 billion) to the offering. However, this commitment is subject to IFC board approval and does not constitute a recommendation to invest. The final subscription level and IPO outcome will only be confirmed after the offer closes.
Johannesburg’s stock exchange still dwarfs Nairobi in size, but the gap is narrowing. Kenya’s reforms and deal flow point to a structural shift, not a short-term bounce. Macroeconomic stability, maturing private equity cycles, and faster regulatory approvals are giving Nairobi a shot at regional dominance in capital markets.
Keeping the momentum will take more than a flurry of deals. Tax policy needs to settle, as shifting capital gains and withholding rules keep long-term investors on edge. Kenya’s pension funds and SACCOs control trillions of shillings, but new incentives are needed to steer more of that money into local debt and equities. Pushing state-owned firms to list publicly, instead of selling off assets in private deals, would boost market size and draw global index trackers. Aligning listing and settlement rules across the East African Community would let Nairobi pull in order flow from Uganda, Tanzania, and Rwanda.
In the past six months, Kenya’s economic base has held firm and capital markets have regained their spark. The next moves on tax, institutional capital, privatisation, and regional rules will decide how far Nairobi can push its lead as East Africa’s financial hub.